India Data Center Market Outlook 2021-2031F
Market Size, Share, Trends, Opportunities, and Competitive Analysis - Segmented by Type (Colocation, Hyperscale, Enterprise, and Edge); Tier (Tier I and II, Tier III, and Tier IV); End User (IT and Telecom, BFSI, Government, E-Commerce, Manufacturing, and Others); and Region
India Data Center Capacity to Nearly Quadruple to 6.4 GW by 2031, Growing at a 26% CAGR: How AI, Hyperscalers and a 2047 Tax Holiday Are Reshaping the Market
1.6 GW MARKET SIZE, 2025 | 6.4 GW MARKET SIZE, 2031F |
34% CAGR, 2021-2025 | 26% CAGR, 2026E-2031F |
India Data Center Market Overview
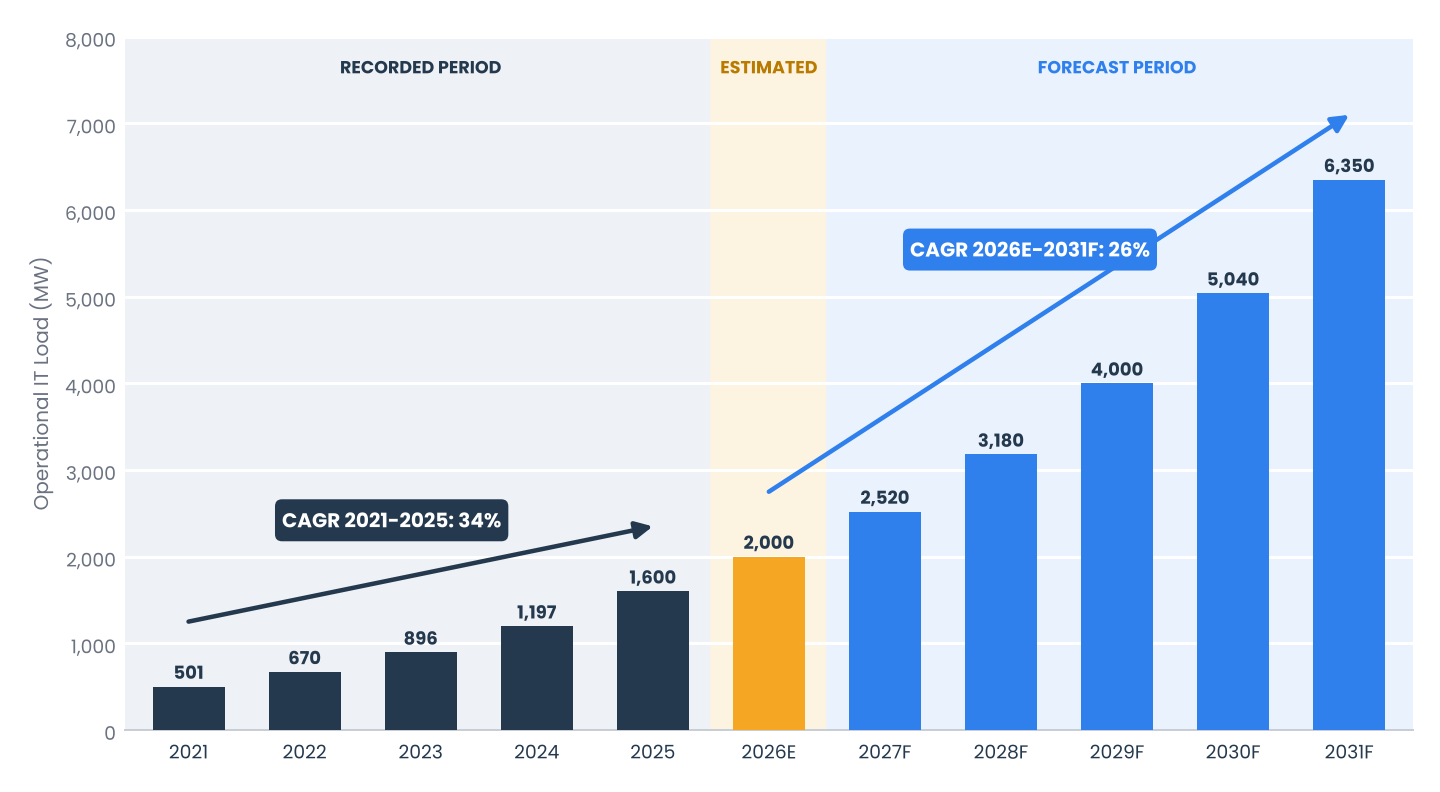
India’s data center market is in a period of rapid build-out. Neargoal Consulting estimates operational capacity grew about 34% a year over 2021-2025 to reach 1.6 GW in 2025 and projects 6.4 GW by 2031, a 26% CAGR, as hyperscalers, AI developers and domestic operators commit capital at scale. Nearly USD 70 billion of investment is underway, with a further USD 90 billion announced, and a proposed tax holiday to 2047 is widening the opportunity. Power, water and land access will decide where and how fast capacity is delivered. The newly released research report quantifies the market by Type, Tier, End user and Region and shows where the next wave of capacity will land.
Key Takeaway India’s capacity is set to surpass 6 GW by 2031, but delivery will depend on power, water and land more than on capital. The operators and investors that secure all three early will capture a disproportionate share of the growth. |
Table 1: India Data Center Market: Key Insights
Metric | Finding |
Market Definition | Operational IT Load Capacity (MW) of Commercial and Enterprise Data Centers in India |
Base Year / Estimated Year | 2025 / 2026E |
Forecast Period | 2027F-2031F |
Market Size, 2025 | 1.6 GW |
Market Size, 2031F | 6.4 GW |
Historical CAGR, 2021-2025 | 34% |
Forecast CAGR, 2026E-2031F | 26% |
Dominant Segment, By Type | Colocation |
Dominant End User | IT and Telecom |
Dominant Tier | Tier III |
Key Growth End Users | BFSI and Government |
Largest City | Mumbai |
Emerging Hubs | Visakhapatnam, Hyderabad, Kolkata and Ahmedabad |
Investment Pipeline | Nearly USD 70 Billion Underway; USD 90 Billion Announced |
Key Constraints | Power, Water, Land and GPU Supply |
Source: Neargoal Consulting Analysis
Market Outlook
Our study estimates India’s operational data center capacity will rise at 26% forecast CAGR (2026E-2031F), which is below the 34% recorded over 2021-2025 because the base is larger and growth is increasingly gated by grid connections, water and equipment supply rather than demand. Our analysis expects hyperscale and AI-ready campuses to account for most incremental capacity, with leased capacity serving the bulk of demand. At the 26% CAGR, annual additions rise from about 520 MW in 2027F to about 1,310 MW in 2031F, and 2031F capacity is about 3.2 times the 2026E level.
Figure 1: India Data Center Market Size, 2021-2031F (MW)
Source: Neargoal Consulting Analysis
Market Dynamics
Growth Drivers
- AI and Hyperscale Demand. GPU-dense workloads are raising rack densities and pulling hyperscalers into long-term leasing and self-build programs. The national AI compute mission has onboarded 38,231 GPUs through 14 providers at a subsidized INR 65 per hour.
- Policy Support. The Union Budget 2026–27 proposes a tax holiday until March 2047 for notified foreign cloud providers on income from global services delivered from Indian data centers, with a 15% safe harbor for the related Indian operator.
- Data Gravity. India generates nearly 20% of the world’s data but hosts only about 3% of its data centers, leaving a structural capacity gap.
Restraints
- Power and Land. Access to power-ready land near substations and transmission corridors is the binding constraint in most major markets.
- Water. Water is limited in several hubs, and Mumbai (one of the key regional drivers) imposed supply cuts on industrial and commercial users in mid-2026.
- Hardware Supply. GPU demand and high-bandwidth memory shortages are raising costs and can delay well-funded projects.
Opportunities
- Second-Tier Cities and Edge. Smaller cities and edge sites start from a small base but offer land, power and low-latency demand beyond the saturated metros.
- Closed-Loop and Liquid Cooling. These systems support the rack densities of AI workloads while easing pressure on scarce water.
- Renewable Power with Storage. Procuring renewable power backed by battery storage helps operators secure supply where grid access is tight.
- GPU-as-a-Service. Operators that cannot fund hyperscale builds can still serve AI demand by offering GPU capacity as a service.
Policy and Regulatory Landscape
The tax holiday proposed in the Union Budget 2026–27 applies where the foreign provider is notified, the data center meets criteria notified by the government and is owned and operated by an Indian company, and services are delivered to global clients. Services to Indian customers must go through a taxed Indian reseller. A draft National Data Centre Policy proposes conditional tax exemptions and single-window clearances, and the Economic Survey 2025–26 flags power, water and hardware supply as bottlenecks.
Segment Insights
By Type, Colocation leads, serving hyperscalers and enterprises that prefer leased capacity to self-build. Hyperscale is the main growth engine within the type split, as AI-ready campuses account for most incremental capacity. The full report quantifies every segment; the highlights below cover Tier and End user segments.
By Tier
Tier III facilities, built so equipment can be serviced without a shutdown, dominate the market because they suit the leased capacity that hyperscalers and enterprises prefer. Tier IV facilities, designed to tolerate any single fault, are scarcer and costlier, and are sought by banks, payment processors and government workloads that cannot afford downtime. Tier I and II sites remain in use for smaller enterprise rooms and edge deployments. As AI clusters raise rack densities, our analysis expects demand to shift toward higher-tier, liquid-cooled halls, with Tier III still absorbing most new leased capacity.
By End User
- IT and Telecom. The largest end user: cloud platforms, telecom operators and digital-content firms anchor most leased capacity.
- BFSI. Banks, insurers and payment firms must keep payment and customer data in India, supporting demand for resilient, higher-tier capacity and disaster-recovery sites.
- Government. Sovereign compute and public-sector cloud programs, including the national AI mission, create steady demand for secure capacity.
- E-Commerce and Manufacturing. Retail platforms need peak-season capacity close to users, while smart factories are creating early edge demand.
Geographic Insights
Mumbai is the largest hub, with Maharashtra holding about two-thirds of national capacity, helped by subsea cable landings and dense enterprise demand. The next wave is moving south and east, where land, power and state incentives are stronger.
- Chennai and Delhi-NCR. Chennai is a second cable gateway with strong southern enterprise demand, while Delhi-NCR is the center of government and BFSI demand in the north.
- Visakhapatnam. Anchored by a 1 GW AI campus whose foundation stone was laid in April 2026, with AdaniConneX and Airtel.
- Hyderabad, Kolkata and Ahmedabad. Emerging hubs offering land and power availability beyond the saturated metros.
Competitive Landscape
Key participants include NTT Global Data Centers, STT GDC India, CtrlS, Nxtra by Airtel, Sify, AdaniConneX, Yotta, Equinix, Digital Realty, Reliance and Tata Communications. Competition is shifting from floor space to secured power, renewable supply and hyperscale anchor tenants. Operator profiles and positioning are covered in the full report.
|
|
|
|
|
|
|
|
|
|
|
Logos are trademarks of their respective owners, shown for identification only; no affiliation or endorsement is implied.
Key Developments, 2025-2026
- September 2026. Sify Infinit Spaces puts its IPO of about INR 37 billion (~USD 390 million) on hold over a valuation gap, months after receiving SEBI approval; ESDS, an India-based enterprise cloud,
GPU, data center and AI infrastructure enterprise, has list in September, 2026. - June 2026. Meta agrees to lease 168 MW of AI data center capacity from Reliance in Jamnagar; CPP Investments commits about USD 740 million to CtrlS.
- April 2026. Foundation stone laid for Google’s 1 GW AI data center campus at Visakhapatnam, valued at about USD 15 billion.
- March 2026. Airtel announces USD 1 billion of investment in Nxtra, led by Alpha Wave Global and Carlyle.
What This Means for Decision-Makers
- Hyperscalers and AI Developers: Secure power and land early; second-tier city hubs offer capacity but need grid proof.
- Operators: Differentiate on secured power, water-efficient cooling and AI-ready density.
- Investors: Underwrite on delivered and contracted capacity, not announced megawatts.
- Equipment and Cooling Suppliers: Demand is shifting to liquid cooling, power systems and storage.
About the Report
Table 2: India Data Center Market: Report Coverage
Coverage Area | What the Report Covers |
Market Size and Forecast | Capacity (MW) and Investment (USD) Views, 2021-2031F |
Segmentation | Type, Tier, End User and Region |
Geography | Mumbai, Chennai, Delhi-NCR, Hyderabad, Bengaluru, Visakhapatnam, Kolkata, Ahmedabad and Other Second-Tier Cities |
Competition | Market Concentration, Strategic Moves, Listings and Operator Profiles |
Policy and Constraints | Union Budget 2026–27, Draft National Policy, Power, Water and Hardware Supply |
Outlook and Recommendations | White-Space Assessment and Guidance by Stakeholder |
Source: Neargoal Consulting Analysis
The research report, India Data Center Market Outlook 2021-2031F - Market Size, Share, Trends, Opportunities, and Competitive Analysis - Segmented by Type (Colocation, Hyperscale, Enterprise, and Edge); Tier (Tier I and II, Tier III, and Tier IV); End User (IT and Telecom, BFSI, Government, E-Commerce, Manufacturing, and Others); and Region, covers commercial (colocation and hyperscale) and enterprise data centers in India, with a 2025 base year, a 2026E estimate and a 2027F-2031F forecast. It excludes telecom core networks, consumer cloud storage and on-premise server rooms below 1,000 sq ft. Market estimates and projections are based on Neargoal Consulting’s proprietary research methodology, exhaustive primary and secondary research.
For questions about report coverage, methodology, suitability, etc.
For requirements beyond the published report