
India Data Center Market to Surpass 6 GW by 2031: Neargoal Consulting Finds Colocation, Hyperscale Demand and a 2047 Tax Holiday Driving the Build-Out
Operational capacity is set to nearly quadruple by 2031, with colocation anchoring supply and power and water availability setting the pace
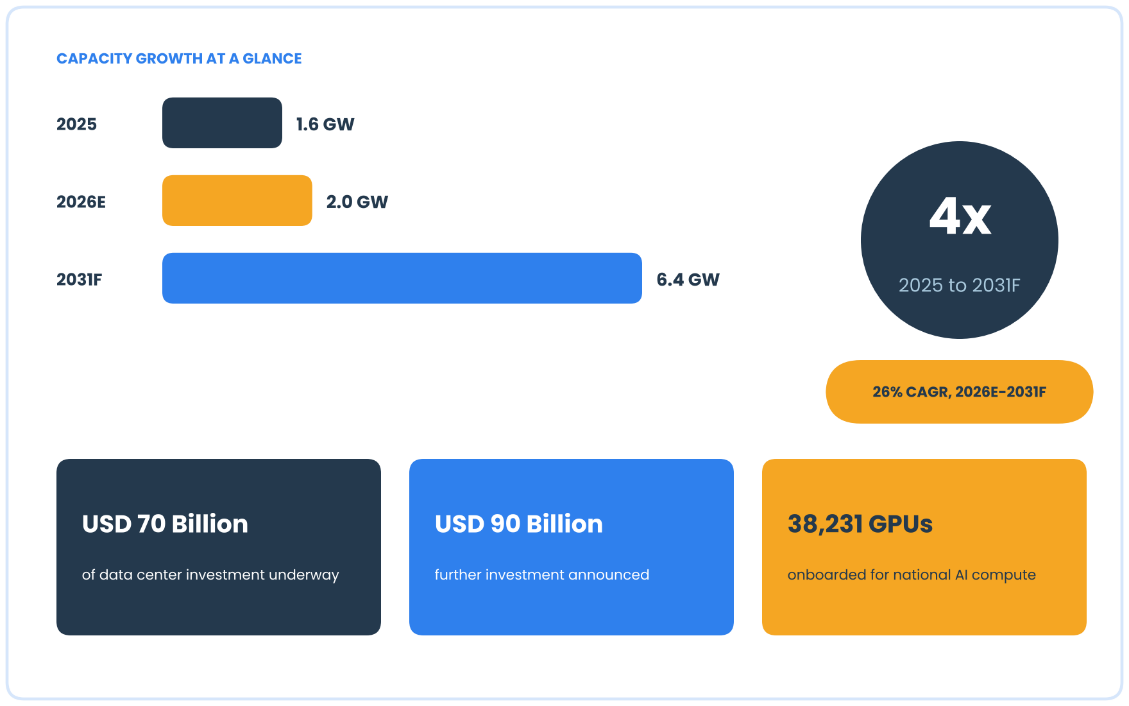
India Data Center Market Outlook 2021-2031F, a research report published by Neargoal Consulting, projects operational capacity of the country’s data center market to reach 6.4 GW by 2031, up from 1.6 GW in 2025. Capacity is expected to grow at a 26% CAGR over 2026E-2031F, after expanding about 34% a year over 2021-2025. Demand is driven by AI workloads, hyperscale cloud commitments and a tax holiday proposed to run until 2047, with nearly USD 70 billion of investment underway and a further USD 90 billion announced.
Figure 1: India Data Center Capacity and Investment Snapshot, 2025-2031F
Source: Neargoal Consulting Analysis
Key Findings
1. Market Outlook. Operational capacity is projected to rise from 1.6 GW in 2025 to 2.0 GW in 2026E and 6.4 GW by 2031F, a 26% CAGR over 2026E-2031F.
2. Colocation Leads. Colocation is the largest segment by type, as enterprises, cloud providers and AI developers lease capacity rather than build and operate their own facilities.
3. Hyperscale is the Growth Engine. Google is building a 1 GW campus at Visakhapatnam, Meta will lease 168 MW from Reliance in Jamnagar, and the government has onboarded 38,231 GPUs for national AI compute.
4. Edge and Second-Tier Cities Are the White Space. Edge and smaller-city capacity starts from a small base but is positioned to gain share as latency-sensitive and data-localization workloads spread beyond the metros.
5. Policy Tailwind. The Union Budget 2026–27 proposes a tax holiday until March 2047 for notified foreign cloud providers, with a 15% safe harbor for the related Indian operator.
6. Investment Pipeline. Nearly USD 70 billion of data center investment is underway, with a further USD 90 billion announced, according to Government Sources.
7. Capital Markets. Airtel’s Nxtra has secured USD 1 billion, CPP Investments has committed about USD 740 million to CtrlS, and ESDS has listed, while Sify Infinit Spaces has put its IPO on hold over valuation.
Segment Spotlight: Colocation, Hyperscale and Edge
By type, the market splits into Colocation, Hyperscale, Enterprise and Edge facilities. Colocation is the largest segment, and its lead rests on a simple economic logic: leasing ready capacity is faster and less capital-intensive than building it, which suits cloud providers, banks, telecom operators and a growing group of AI developers competing for scarce power. Operators that can offer dense, liquid-cooled halls and reliable grid connections are best placed to win these leases.
Hyperscale capacity is the fastest-scaling part of the market, as large cloud and AI platforms commit to multi-hundred-megawatt campuses, often through long-term leases with domestic operators. Enterprise facilities, by contrast, are gradually giving way to colocation and cloud, while edge sites, though small in capacity, are expanding in second-tier cities to serve low-latency applications. The study also examines how each segment varies by tier and end user, and how that mix differs across regions.
Why It Matters
Capital is moving faster than the infrastructure that supports it. The Economic Survey 2025–26 flags power, water and hardware supply as binding constraints, and the gap between announced and deliverable capacity is visible in water-stressed hubs such as Mumbai. Operators, investors and suppliers that understand where capacity will land, and when, will be better placed to commit capital.
Report Coverage
Key participants shaping the market include NTT Global Data Centers, STT GDC India, CtrlS, Nxtra by Airtel, Sify, AdaniConneX, Yotta, Equinix, Digital Realty, Reliance and Tata Communications, among others.
The research report, India Data Center Market Outlook 2021-2031F - Market Size, Share, Trends, Opportunities, and Competitive Analysis - Segmented by Type (Colocation, Hyperscale, Enterprise, and Edge); Tier (Tier I and II, Tier III, and Tier IV); End User (IT and Telecom, BFSI, Government, E-Commerce, Manufacturing, and Others); and Region, covers market size and forecast, segmentation, regional and city analysis, policy and constraints, competitive landscape and operator profiles. Market estimates and projections are based on Neargoal Consulting’s proprietary research methodology, exhaustive primary and secondary research.
To request a sample or the full table of contents, visit neargoal.com.
About Neargoal Consulting
Neargoal Consulting is a market intelligence and advisory firm delivering analyst-led, evidence-validated research across Energy, Chemicals, Automotive & EV, Digital Technologies, Consumer & Retail, Healthcare, and Defense. Every engagement is built around the decision it needs to support. For more information, visit neargoal.com.